Disclaimer: This article is provided for informational purposes only and is not intended as financial advice. Individual circumstances vary. Consumers should consider their own financial situation and consult a qualified professional regarding their specific needs.
Subject to eligibility and approval. Spending power not guaranteed. Platform charges and late fees may apply. Some retailers require a Four+ subscription. Not available in NM. Not all applicants are approved. Results may vary. Wondering how buy now pay later compares with paying by credit card at checkout? Many buy now pay later services offer installment plans that split a purchase into several payments over a set period, but schedules, eligibility, credit checks and costs vary by provider. Knowing the terms upfront helps you see what a purchase may cost.
TLDR:
- Most pay-in-four BNPL plans split a purchase into four payments over about six weeks, and terms vary by provider. Four does not charge interest, but platform charges for automatic payments and late fees may still apply.
- Eligibility and credit-check requirements vary by provider and plan, so review the terms before applying
- Longer monthly BNPL plans often carry APR, so check the terms before selecting one at checkout
- Four requires no credit check when signing up, and eligible users may receive a one-time virtual card after a decision. Not all applicants are approved. Results may vary. Built-in payment reminders notify you before each scheduled payment; Four collects payments automatically on your scheduled due dates and a platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date. Platform charges and late fees may apply.
What Is Buy Now Pay Later?
Buy now pay later is often a short-term installment plan offered at checkout. Instead of paying the full price upfront, you split a purchase into a set number of payments. With many pay-in-four plans, that means four payments spread over several weeks, and interest, charges, and late fees vary by provider. Many BNPL plans do not require a credit card.
How Buy Now Pay Later Works at Checkout
Here is how checkout with Four works. Other providers' steps and schedules may differ.
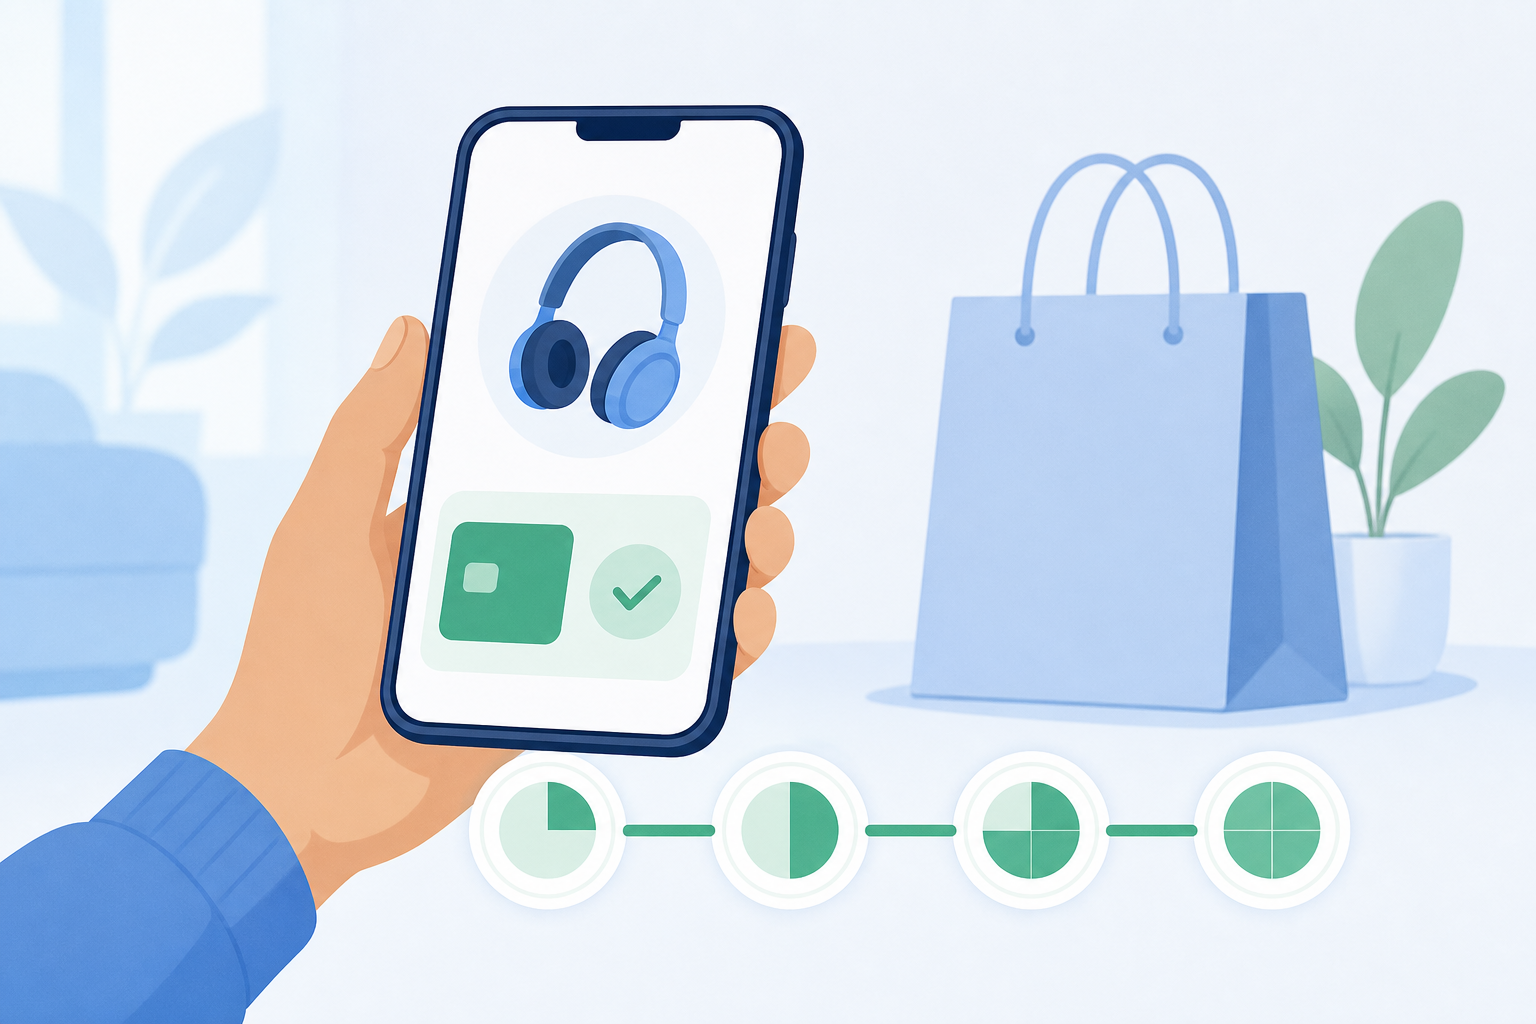
- You shop at a participating retailer available in the Four app.
- Four provides an instant decisioning result. Not all applicants are approved. Results may vary.
- You pay the first installment immediately.
- With Four, the remaining three payments are due every two weeks after the first payment.
With app-based buy now pay later like Four, you browse participating retailers available inside the Four app and receive a decision. Not all applicants are approved. Results may vary. If approved, Four issues a one-time virtual card to use at checkout. At Four, customers make four payments over six weeks.
Some retailers embed BNPL directly into their checkout, without a separate app. If a retailer offers this option, review the provider's terms and application steps before choosing it.
Either way, the BNPL payment structure is often similar: you pay a portion now and the rest later, typically on a fixed schedule.
The Pay-in-Four Model Explained
The Four pay-in-four structure divides your purchase into four easy payments. The first is due at checkout, and the remaining three follow every two weeks until the balance is paid off, putting the full repayment window at six weeks.
Check whether a provider collects payments automatically, which payment method it uses, and when each payment is due.
Longer-Term Monthly BNPL Plans
Some BNPL providers offer longer monthly installment plans, with repayment schedules and costs set out in each provider's terms. Before choosing one, check the number of payments and the total repayment amount.
Before confirming one of these monthly BNPL plans, check whether interest applies, review the APR if one is listed, and calculate the total repayment amount. The monthly payment may look small, but the total cost over the repayment period may add up.
What BNPL Costs: Fees and Interest Explained
Interest and fees vary by BNPL provider. Four does not charge interest on its installments, but platform charges and late fees may apply. A plan that charges no interest may still carry other costs.
Platform charges and late fees may apply. Four collects payments automatically on your scheduled due dates. A platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date.
Longer-term monthly plans are a different product. Read the offered terms for any such plan, and check interest, charges, and due dates before selecting one.
Total amount payable, applicable charges, and due dates differ across payment options, and some shoppers compare them before choosing one.
How BNPL Affects Your Credit Score
Whether a pay-in-four plan affects your credit score depends on the provider, so check its current credit-check and payment-reporting terms before applying. Some providers do not report BNPL payments, and some do. Affirm, for example, sends payment updates to Experian and TransUnion once a month. BNPL credit reporting practices may change. If a provider does not report payments, on-time payments won't build your credit history, and a payment that becomes late may still lead to late fees.
Why Merchants Offer BNPL and What It Costs You as a Shopper
Seeing an installment option at checkout does not by itself tell you the total cost of a purchase. Review the payment schedule and any charges offered before confirming an order.
With Four, platform charges and late fees may apply. Review the charges shown for your order before you confirm it.
The Approval Process and Eligibility
Eligibility, identity information, and credit-check requirements vary by provider and plan. Check the specific requirements for any BNPL service before applying.
Before applying, check the provider’s eligibility and payment-method requirements:
- Check the minimum age required to apply
- Check whether the service is available where you live
- Check which payment methods a provider accepts, such as a debit card, bank account, or other supported option, before you apply
Not all applicants are approved. Results may vary. Spending power varies by user and transaction. Some orders may be declined even if a previous one went through.
BNPL vs. Credit Cards: Key Differences
The structural difference that matters most: credit cards typically let you carry a balance, with interest accruing on what remains unpaid. Many BNPL plans set a fixed installment schedule. A late payment does not erase what you owe, and a late fee or other charge may apply. Each option's terms list its due dates and payment obligations.
Credit cards and BNPL plans work differently, and the repayment schedule, total charges, and dispute or refund terms differ by option. For some users, checking what they already owe and when each payment is due is helpful before adding another plan. Stacking multiple active BNPL plans at once may stretch a budget in ways that are easy to underestimate.
Feature | BNPL (Pay-in-Four) | Credit Card |
|---|---|---|
Interest | Check the offered terms; platform charges and late fees may apply | Check the offered terms; APR set by issuer |
Credit check | Check the offered terms; requirements vary by provider | Check the offered terms; requirements vary by issuer |
Repayment | With Four, the first payment is due at checkout and the remaining three follow every two weeks; check the offered repayment dates for other providers | Check the offered terms for minimum payment requirements |
Credit reporting | Check the offered terms; reporting policy varies by provider | Check the offered terms; reporting policy varies by issuer |
Purchase approval | With Four, approval varies by user and transaction. Not all applicants are approved. Results may vary. | Check the offered terms; approval varies by issuer and applicant |
Late fees | Check the offered terms; platform charges and late fees may apply | Check the offered terms; late fees vary by issuer |
This comparison reflects most standard pay-in-four BNPL plans. Terms vary by provider. Check each company's terms before committing.
Pros and Cons of Buy Now Pay Later
Buy now pay later has real advantages, but it comes with tradeoffs worth knowing before you commit.
Pros
- Four does not charge interest on its installments, but platform charges and late fees may apply.
- Four offers a one-time virtual card for checkout if a purchase is approved. Not all applicants are approved. Results may vary.
- With many BNPL plans, a fixed repayment schedule may make each installment easier to anticipate
- Four does not require a credit check or Social Security Number when signing up
Cons
- It may be easy to stack multiple active BNPL plans and lose track of your total obligations across purchases
- With Four, platform charges and late fees may apply. Check applicable charges and due dates before confirming a purchase.
Tips for Managing Multiple BNPL Payments
Each BNPL plan has its own due dates, and with several active plans those dates may not line up with each other or with a paycheck. For some users, these habits are helpful:
- Some users track every active plan in one place, such as a notes app, a spreadsheet, or the BNPL app itself.
- Some users turn on payment reminders to get notice before each scheduled automatic payment; see Four's SMS terms and conditions for how text alerts work.
- Keep in mind: Four collects payments automatically on your scheduled due dates, and a platform charge applies to those automatic payments. To avoid that charge, pay manually a minimum of 3 business days before your scheduled due date.
- For some users, checking the total outstanding balance before opening a new plan is helpful.
- Some users link a payment method they expect to have funds on each scheduled date.
- Some users avoid opening new plans in the week before a cluster of due dates.
BNPL for People on Fixed Incomes and Tight Budgets
Whether an installment plan fits your fixed income depends on your individual circumstances, the total charges involved, and when each payment is due. At Four, customers will make four payments over six weeks. Platform charges and late fees may apply. Four collects payments automatically on your scheduled due dates, and a platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date.
Multiple active BNPL plans at once may be harder to manage. Three overlapping installment plans may claim more of each paycheck than expected. Each plan may look manageable on its own, and the combined payments may add up.
If a purchase would strain a budget even when split across four payments, the schedule does not change the total owed. Learn more about Four.
How to Get Started with Four
Getting started takes just minutes. Download the Four app and browse participating retailers inside it. Signing up requires no credit check or SSN. When you're ready to buy, your purchase is subject to approval. Not all applicants are approved. Results may vary. If approved, Four generates a one-time virtual card to use at checkout, your first payment is due at checkout, and the remaining three follow every two weeks.
Four supports Apple Pay and Google Pay. Built-in payment reminders notify you before each scheduled automatic payment. A platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date.
Four+ provides access to exclusive stores and special offers. Some retailers require a Four+ subscription. See the Four+ terms of use for details.
Four is available to U.S. residents 18 and older, except in New Mexico. Platform charges and late fees may apply.
Final Thoughts on How Buy Now Pay Later Works
Four splits a purchase into four easy payments over six weeks with no interest charges on the installments, but platform charges and late fees may apply. For some users, reviewing the full cost and due dates before confirming is helpful.
FAQ
How does buy now pay later work and how do I get started with Four?
Most pay-in-four plans spread a purchase across several installments; schedules vary by provider. With Four, you download the app and browse participating retailers. Four does not require a credit check or SSN when signing up. Four provides an instant decisioning result. Not all applicants are approved. Results may vary. If approved, you receive a one-time virtual card to complete checkout. At Four, the first payment is due at checkout, and the remaining three follow every two weeks.
How does pay-in-four work for people on a fixed income?
Four spreads a purchase across six weeks with no interest charged on the installments, though platform charges and late fees may apply. No single BNPL option is suitable for every fixed-income shopper; costs, due dates, and individual circumstances vary. Four collects payments automatically on your scheduled due dates. A platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date.
What options are available for tracking multiple buy now pay later payment dates?
For some users, keeping active plans and payment dates in one place is helpful. Four sends built-in reminders before each installment is due. Four collects payments automatically on your scheduled due dates. A platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date.
How does Four disclose fees compared with Afterpay, Affirm, and Klarna?
Four discloses fees before you confirm an order. Platform charges and late fees may apply. Four collects payments automatically on your scheduled due dates. A platform charge applies to automatic payments. To avoid the platform charge, you must pay manually a minimum of 3 business days before your scheduled due date. Terms vary by provider and plan; this article does not rank apps by fee transparency.
Does using buy now pay later with Four or Afterpay affect your credit score?
Credit reporting varies by provider and plan. Some providers do not report BNPL payments, and some do. Affirm, for example, sends payment updates to Experian and TransUnion once a month. FICO's optional Score 10 BNPL and Score 10 T BNPL models may use reported BNPL data, but the existence of these models does not mean every provider reports payments. Whether BNPL activity affects a credit score depends on whether the provider reports it and which scoring model a lender uses. A scheduled payment that fails to process and becomes late may affect a score if it is reported and the scoring model uses it. To find out whether Four or Afterpay reports a particular plan, check each company's own terms.