Disclaimer: This article is provided for informational purposes only and is not intended as financial advice. Individual circumstances vary. Consumers should consider their own financial situation and consult a qualified professional regarding their specific needs.
Thinking of adding BNPL to your store, but unsure what happens after a customer clicks it? You generally get paid upfront while the provider collects installments, but processing fees, settlement timing, and refunds still affect your business. Your shoppers have their own questions about due dates and total costs. Following the payment from checkout through repayment makes it easier to see what both sides should check.
TLDR:
- Pay-in-four BNPL typically splits your purchase into four payments over six weeks.
- Check total costs before accepting. No interest does not mean no fees.
- Match your installments to income dates and track all plans in one budgeting app.
- Merchants typically receive funds upfront but pay fees; compare costs against your margins.
- Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. No SSN is required to sign up. Four's platform charge of up to $3 per installment applies to automatic payments, is disclosed at order setup, and can be avoided by paying manually at least three business days before the due date. Platform charges and late fees may apply.
What Is Buy Now, Pay Later?
A buy now pay later payment lets you split a purchase into installments over time. Offered by third-party payment providers, BNPL helps shoppers spread out spending online or in store.
According to the Richmond Fed, U.S. pay-in-four BNPL transaction value reached an estimated $70 billion in 2025, growing roughly 20 percent annually in real terms since 2021.
How a BNPL Payment Works at Checkout
A buy now pay later payment generally follows these checkout steps:
- Select the BNPL option at checkout.
- Enter the requested details and a repayment method, then submit for approval.
- If approved, review installment amounts, due dates, and any fees or interest.
- Accept the terms and complete the purchase, including any payment due immediately.
- Save the confirmation and payment schedule for your records.
Common BNPL Repayment Structures
A buy now pay later payment schedule varies by provider and purchase amount. Two common formats are:
Format | Typical schedule |
|---|---|
Pay in four | One payment at purchase, then three payments every two weeks, spanning six weeks. |
Monthly installments | Monthly payments over several months or, for some plans, years. |
Check the final due date and total repayment amount before choosing. A smaller monthly payment may mean a longer commitment.
Does BNPL Require a Credit Check?
Most pay-in-four BNPL products use a soft credit inquiry, which does not affect your credit scores. Some providers skip credit checks entirely. Four is one of them: Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. No SSN is required to sign up, and approval decisions come in real time.
Longer-term installment plans sometimes require a hard inquiry, which may temporarily lower your score.
Before choosing a buy now pay later payment option, check its inquiry policy. Credit checks and payment reporting are separate: a soft inquiry does not tell you whether later payment activity will be reported.
How BNPL Affects Your Credit Score
Credit reporting for a buy now pay later payment plan varies by provider, so check whether yours reports repayment activity to credit bureaus. On-time payments won't build your credit history if they aren't reported; reported activity may affect your score.
Missed payments may hurt your credit score if reported. Unpaid balances may also go to collections and appear on your credit report, even if routine payments were never reported.
BNPL vs. Credit Cards: Key Differences
Factor | BNPL | Credit cards |
|---|---|---|
Interest | Some plans charge interest; others don’t. | Carrying a balance may incur interest. |
Approval | Varies by provider and plan. | Generally depends on credit history and income. |
Spending flexibility | Approval typically covers one purchase. | Reusable credit limit for ongoing purchases. |
Missed payments | Possible late fees or account restrictions. | Possible late fees and penalty interest rates. |
Compare total costs against your expected repayment timeline, whether you're shopping at a department store like Nordstrom or elsewhere.
Fees, Costs, and What to Watch Out For
Many buy now pay later payment plans charge no interest when you pay on time, but costs vary by provider. Check the terms before accepting:
- Service charges may apply to installments even when paid on time.
- Longer-term plans may carry APR-based interest.
- Most providers charge late fees for missed payments, according to CFPB missed-payment guidance.
No interest does not mean no fees.
How to Manage Multiple BNPL Payments Without Missing Due Dates
Nearly half of BNPL users paid late in the past year, according to LendingTree's BNPL payment tracker. Keep commitments across providers in one view:
- Track balances and installments in a budgeting app.
- Use autopay and check funds before withdrawals.
- Request due dates after payday where changes are allowed.
- Set reminders before payments.
- Before another buy now pay later payment commitment, check whether its installments leave enough for everyday expenses.
BNPL for People on Fixed or Limited Incomes
On a fixed income or tight budget, a buy now pay later payment plan may help spread costs. Biweekly installments may fit pay arriving every two weeks; monthly benefits or irregular paychecks need closer planning.
Before accepting, compare repayment dates with expected income. BNPL approval may not account for what remains after rent and groceries. Stacking BNPL plans may commit much of your next deposit before it arrives, leaving little room for unexpected bills.
How BNPL Works for Merchants
For merchants, a buy now pay later payment typically means receiving funds upfront while the provider collects customer installments. Merchants generally pay a percentage of the sale plus a fixed fee, though rates vary by provider. Four is built so merchants get paid upfront while shoppers split the purchase into four payments, and shoppers can use Four at retailers like The Home Depot, subject to availability shown in the app. Some retailers require a Four+ subscription. Check refund fees and settlement timing before signing.
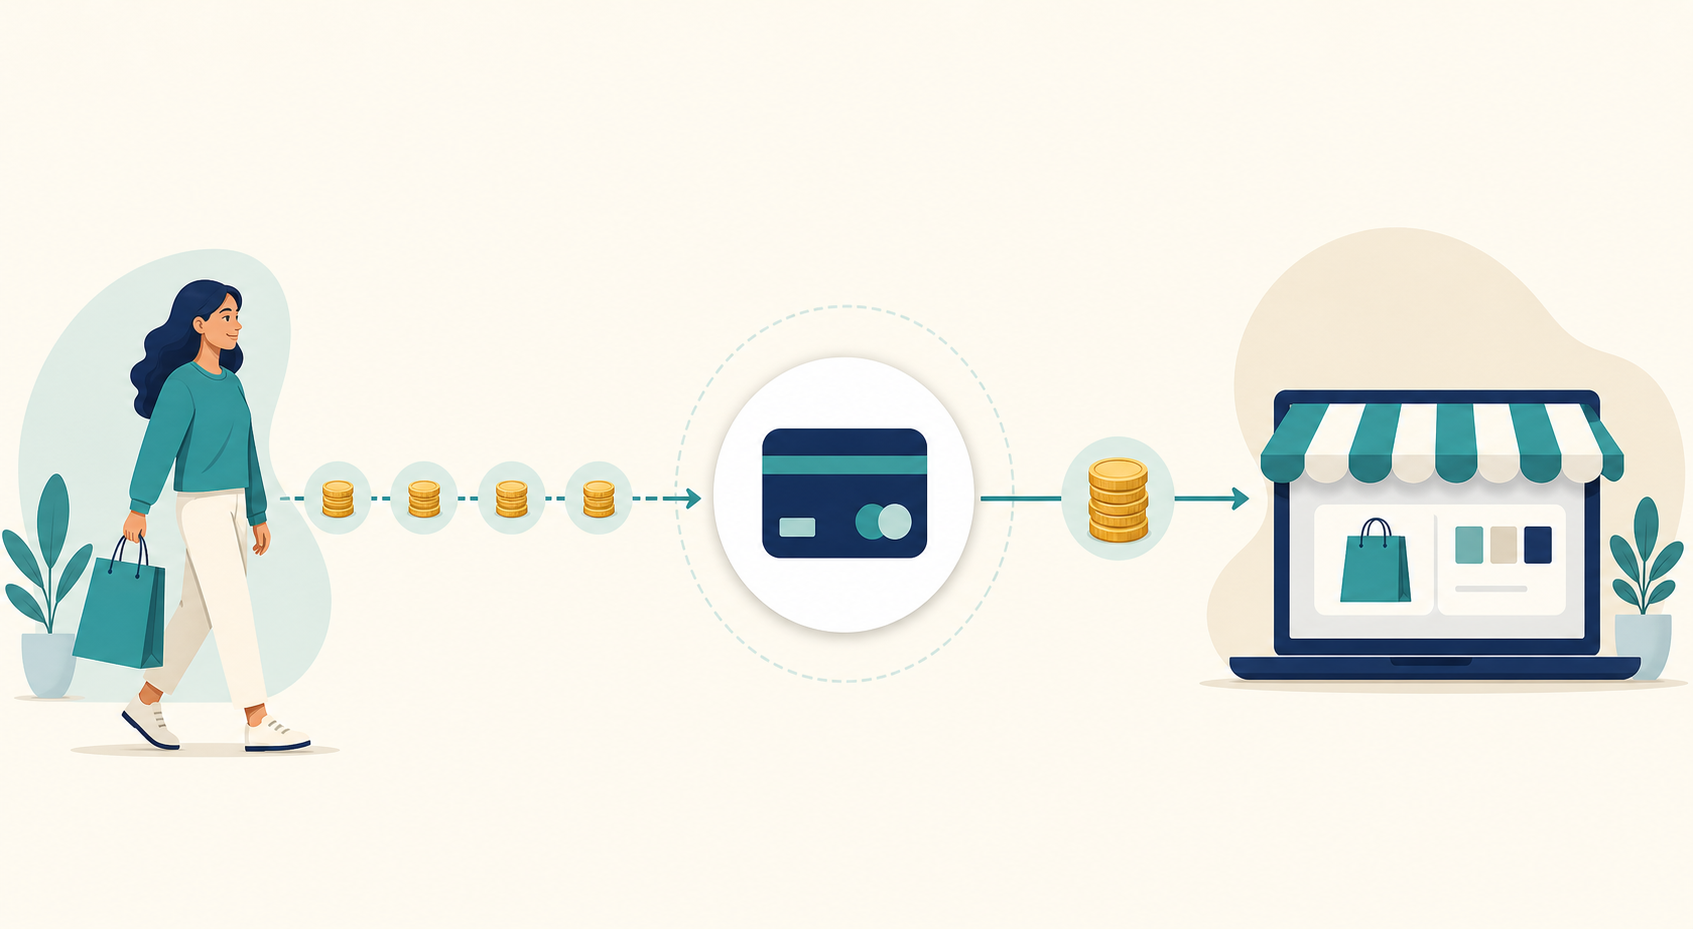
Offering BNPL may give shoppers another way to complete a purchase, but results vary by merchant, customer base, order value, fees, and checkout experience. Merchants should compare any change in completed sales with processing costs, refunds, and product margins.
How Small Online Retailers Can Offer BNPL
To offer a buy now pay later payment option, start with integrations your e-commerce software supports.
- Choose a provider with a compatible plugin, payment gateway connection, or API.
- Prepare business registration, ownership, and bank details; onboarding requirements vary.
- Compare customer eligibility, merchant support, and refund handling before applying.
- After approval, configure checkout and display payment options on product pages.
- Test checkout, order confirmation, and refunds before accepting live BNPL transactions. For a shopper's view, see how Four works at retailers such as Fanatics.
BNPL Regulation and Consumer Protections in the U.S.
U.S. BNPL rules are still taking shape. The CFPB withdrew its 2024 BNPL interpretive rule in May 2025. State requirements may still apply. For example, New York enacted a BNPL law in May 2025 that establishes a licensing and supervisory framework, while the New York Department of Financial Services has continued developing implementing regulations. Legal requirements vary by jurisdiction and product structure. Withdrawal of the interpretive rule does not eliminate other federal or state laws that may apply to a BNPL provider or product. Legal treatment varies by product, so credit-card protections may not apply to every buy now pay later payment plan, whether used at an apparel brand like Adidas or elsewhere.
Before using BNPL, check:
- How to dispute incorrect charges and the deadlines.
- Whether payments continue during a pending return or refund.
- What purchase and personal data the provider shares.
Keep receipts and correspondence, whether you're shopping at a discount retailer like Nordstrom Rack or a full-price store. Retailer return approval and provider payment adjustments are separate steps.
How Four Brings Transparency to the BNPL Payment Experience
Four is a buy now pay later app that splits your online purchase into four interest-free payments: the first at checkout, then one every two weeks. Platform charges and late fees may apply. Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. No SSN is required to sign up. A one-time virtual card handles checkout, whether you're shopping at an activewear brand like alo or another retailer, and Four sends a reminder before each payment is due. Four's platform charge of up to $3 per installment applies to automatic payments, is disclosed during order setup, and can be avoided by paying manually at least three business days before the due date. Four's late fees may include $7 after a missed due date and an additional $8 after seven days, or a $10 flat late fee in select states.
Subject to eligibility and approval. Spending power not guaranteed. Platform charges and late fees may apply. Some retailers require a Four+ subscription. Not available in NM. See Four's additional disclosures.
Final thoughts on Understanding BNPL Costs
No interest doesn't always mean no fees. You deserve to know what your purchase will cost before accepting a plan. Check the terms, then plan each payment around your income.
FAQ
Should you choose Four or a credit card you can pay off in full?
Compare Four’s disclosed fees with the cost of paying your card’s statement balance in full by its due date. If your card offers an interest-free grace period and no applicable purchase fees, it may cost less: Four’s platform charges for automatic payments may total up to $12 across four installments. Platform charges can be avoided by paying each installment manually at least three business days before its due date. Platform charges and late fees may apply.
Is offering Four worth it if your store has thin profit margins?
Offer Four only if the expected profit from extra sales outweighs merchant fees and related costs. For example, if a $100 order leaves $20 before payment processing, subtract the quoted BNPL fee from that $20, then account for refunds and other costs before deciding. This is a hypothetical illustration, not a calculation based on Four’s actual merchant fee structure. Ask Four for current merchant pricing and settlement terms; shopper fees do not tell you what your store will pay.
How do you handle a return when your Four payment is due before the refund arrives?
Do not assume a retailer’s return approval cancels your next Four payment; check your payment schedule and ask Four whether the installment remains due. Keep the return receipt and refund confirmation, and continue following the active schedule unless Four confirms an adjustment. If paying while the refund is pending would cause hardship, contact support before the due date.