Disclaimer: This article is provided for informational purposes only and is not intended as financial advice. Individual circumstances vary. Consumers should consider their own financial situation and consult a qualified professional regarding their specific needs.
Wondering how installment plans work without a hard credit pull? Terms vary by plan, and a plan with no hard inquiry may still involve a soft check, fees, or payment reporting. The consent wording, payment reporting, and repayment dates in a plan's terms show whether an offer fits a given budget.
TLDR:
- Many BNPL providers that skip a hard inquiry may use a soft check, which the CFPB says does not affect credit scores (as of October 2026).
- Late payments may result in fees or collection activity. Whether a missed payment affects your credit history or credit score depends on the provider's reporting practices and other circumstances.
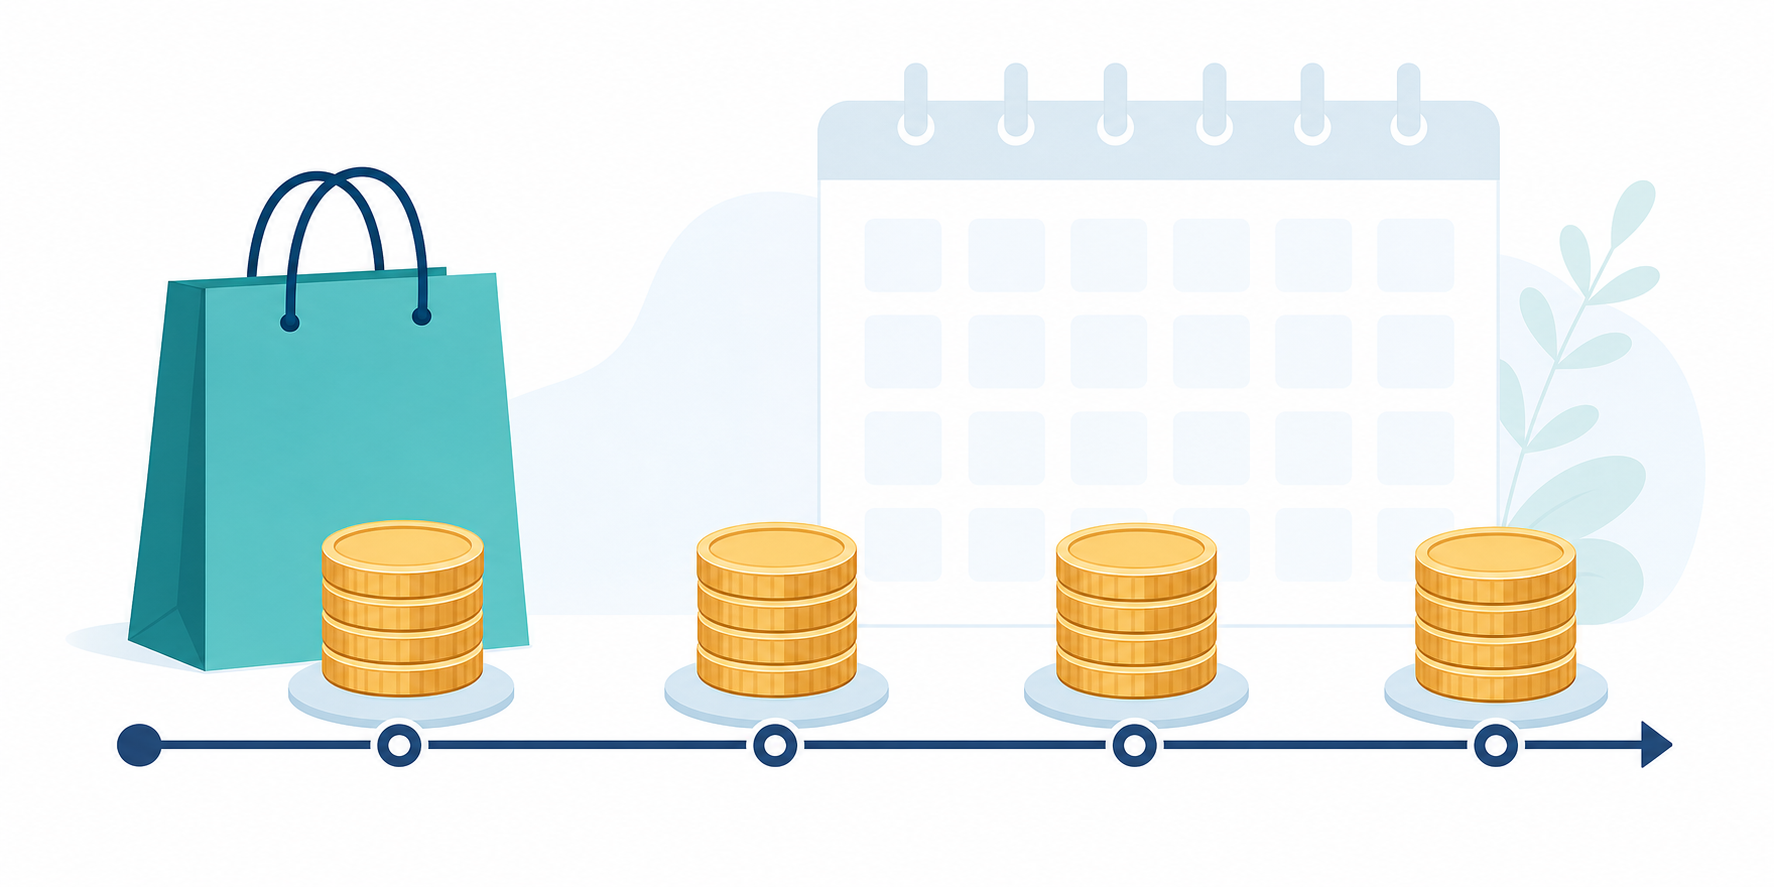
- Most standard pay-in-four plans split a purchase into 4 payments over six weeks, with the first payment at checkout.
- Total repayment on a BNPL plan may differ from the purchase price. Some BNPL plans may charge fees even when they do not charge interest, so consumers should review the total cost before agreeing to a plan.
- Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. With Four, approval is decided separately for each order. Not all applicants are approved. Results may vary. Platform charges and late fees may apply.
What a Hard Credit Inquiry Actually Is
A hard inquiry occurs when a lender accesses your credit file, with your permission, for a credit application. Credit card applications commonly trigger one. As of October 2026, Experian's hard versus soft inquiry guide says that, according to FICO, one hard inquiry typically lowers a score by fewer than five points and may stay on a credit report for up to two years.
A soft credit inquiry includes checking your own report or an existing lender reviewing your account. As of October 2026, the CFPB says soft inquiries do not affect credit scores.
The hard versus soft distinction helps you understand “buy now pay later no hard inquiry” offers: a soft check may still occur.
How BNPL Approvals Work Without a Hard Inquiry
Buy now pay later with no hard inquiry may involve a soft credit check and factors such as order history, purchase amount, and repayment track record with that provider. Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. To see how approvals work at Four, read how Four works.
Many providers use automated systems to process those signals quickly, so some shoppers may receive a decision during checkout. Approval still depends on the provider's criteria.
The Soft Credit Check Explained
With a soft check, a BNPL provider may review your credit history. "Soft" describes the inquiry type, not a separate credit score.
As of October 2026, the CFPB says soft inquiries are not visible when others purchase your credit report. Mortgage or auto applications typically involve hard pulls visible to other lenders.
If you want to split eligible purchases into 4 payments with a provider that runs a check, the consent wording for your selected installment option states the inquiry type. Some shoppers look for an explicit statement that the inquiry is soft before authorizing it. Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry.
How BNPL Affects Your Credit Score and Credit History
Buy now pay later with no hard inquiry may still affect your credit after checkout. Approval requirements and payment reporting are separate questions.
- A soft credit check does not affect your score.
- Most BNPL lenders do not currently report pay-in-four loans to credit bureaus, according to the Federal Reserve Board (August 2026 publication, checked October 2026). Some providers do report. As of October 2026, Affirm's help center says Affirm sends updates to Experian and TransUnion once a month. Practices vary by provider. On-time payments that are not reported will not build credit history.
- Late payments may result in fees or collection activity. Whether a missed payment affects your credit history or credit score depends on the provider's reporting practices and other circumstances.
As of October 2026, the Richmond Fed's BNPL research brief (February 2026) says pay-in-four loans generally do not involve hard inquiries, and lenders generally do not report loan performance to credit bureaus.
Common BNPL Repayment Structures
BNPL schedules vary by plan. Plan details that some shoppers look at include the amount due today and whether remaining due dates match their paydays, whether they're shopping at Nordstrom or elsewhere.
Repayment format | Typical schedule | Interest |
|---|---|---|
Pay in four | On most standard pay-in-four plans, the first payment is due at checkout, then three payments every two weeks over six weeks | Typically no interest, though fees may apply |
Monthly installments | Monthly installment plans often have monthly payments over a longer term; an upfront payment may be required | May carry interest |
This comparison reflects most standard pay-in-four BNPL plans. Terms vary by provider - check each company's terms before committing.
With Four, a reminder is sent before each payment is due, including when you pay in 4 at Nike. With Four, payments are collected automatically, and a platform charge applies to automatic payments. To avoid that charge, you must pay manually a minimum of 3 business days before your scheduled due date. Platform charges and late fees may apply. Some users check which payment method covers each installment before confirming checkout.
What BNPL Actually Costs: Fees and Disclosures
Total repayment on a BNPL plan may differ from the purchase price. Some BNPL plans may charge fees even when they do not charge interest, so consumers should review the total cost before agreeing to a plan.
Four does not charge interest, but platform charges for automatic payments and late fees may still apply. With Four, payments are collected automatically, and a platform charge applies to automatic payments. To avoid that charge, you must pay manually a minimum of 3 business days before your scheduled due date. With Four, a late fee may apply if a payment becomes late, and an additional charge may apply if it remains unpaid; amounts vary by state. See the Four user agreement for details.
- With Four, the platform charge is shown during order setup, including when you pay in 4 at Macy's. With Four, a reminder is sent before each payment is due.
- With Four, if an automatic payment fails to go through and becomes late, a late fee may apply. Some users set reminders and keep enough money in their payment account to cover each installment.
Why Some Shoppers Consider BNPL Without a Hard Inquiry
Some shoppers consider buy now pay later with no hard inquiry when the full purchase fits their budget but paying upfront feels tight. Situations where it may come up include:
- Shoppers who prefer to avoid a hard inquiry when considering a payment option.
- Shoppers who use debit only and prefer scheduled installments.
- Shoppers who want to spread a planned expense, like when they pay in 4 at lululemon.
- Shoppers with limited credit history who want options beyond credit cards, subject to approval.
Some shoppers wait on a purchase when installments would compete with rent or groceries, and some leave room in their budget for unexpected expenses.
How Some Users Keep Track of Multiple BNPL Plans
Using several BNPL services may make total commitments harder to track. In a 2026 LendingTree survey (page updated October 2026), 47% of BNPL users reported paying late in the past year. That figure comes from self-reported survey responses and may not reflect a typical outcome, though it shows how easily late payments may happen.
- Some users track every app's payment dates and amounts in one calendar.
- Some users rely on payment reminders where available, such as the reminders Four sends when they pay in 4 at The Home Depot, and then check that each payment processes.
- Some users finish one plan before opening another when several schedules feel hard to manage.
- With most pay-in-four plans, the first installment is a commitment to pay the full purchase. Some users plan how to cover every remaining payment and any fees before checkout.
BNPL vs. Credit Cards: A Side-by-Side Comparison
Factor | BNPL | Credit cards |
|---|---|---|
Application inquiry | Pay-in-four approvals generally use a soft check or none | Applications typically trigger a hard inquiry |
Interest | Standard pay-in-four plans typically charge no interest; fees may apply | Balances carried month to month generally accrue interest |
Credit history | Payment reporting varies by provider | Reported on-time payments may help build credit history |
This comparison reflects most standard pay-in-four BNPL plans. Terms vary by provider - check each company's terms before committing.
Some shoppers weigh a credit card's annual costs against how often they would use it, whether on everyday items or when they pay in 4 at Fanatics. For a planned purchase, some compare a BNPL agreement's total cost with paying by card.
Features vary by provider, card, and BNPL product. Consumers should compare the specific costs, repayment terms, and credit-reporting practices applicable to each option.
How Four Handles Approvals Without a Hard Credit Inquiry
Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. At Four, no Social Security number is required when signing up. Approval decisions are made in real time. Not all applicants are approved. Results may vary.
With Four, you shop through participating retailers available in the Four app and check out with a one-time virtual card. At Four, customers will make four payments over six weeks, including when you pay in 4 at Adidas. Platform charges and late fees may apply. With Four, the first payment is due at checkout and the rest are due every two weeks, and approval is decided in real time for each order, not as an open credit line. Not all applicants are approved. Results may vary.
With Four, payments are collected automatically, and a platform charge applies to automatic payments. To avoid that charge, you must pay manually a minimum of 3 business days before your scheduled due date.
Subject to eligibility and approval. Spending power not guaranteed. Platform charges and late fees may apply. Some retailers require a Four+ subscription. Not available in NM. See Four's additional disclosures.
Final Thoughts on BNPL and Your Credit
Some BNPL plans skip a hard pull while still offering scheduled payments. Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. Payment reporting and fees vary by plan, and each plan's agreement lists its terms. With Four, platform charges and late fees may apply.
FAQ
How does Four's repayment schedule fit a once-a-month income?
With Four, the first payment is due at checkout and the remaining payments are due every two weeks, so the schedule does not automatically match a monthly income schedule. Some users map out the actual due dates against their paydays before checkout. Platform charges and late fees may apply.
How do Four, Afterpay, Klarna, and Affirm compare for buy now pay later with no hard inquiry?
Terms differ by provider and by the specific installment plan offered at checkout. Four does not perform a credit check when you sign up or when evaluating an order, so applying with Four does not result in a hard credit inquiry. For Afterpay, Klarna, and Affirm, the inquiry type, payment-reporting policy, and total fees depend on the selected plan, and each provider lists them in its own terms. Late payments may result in fees or collection activity. Whether a missed payment affects your credit history or credit score depends on the provider's reporting practices and other circumstances. Features vary by provider, card, and BNPL product. Consumers should compare the specific costs, repayment terms, and credit-reporting practices applicable to each option.
How do merchants get started offering Four installment payments at their online store?
Merchants can contact the Four team to get started. With Four, shoppers can split purchases into four payments, and the merchant receives payment upfront, with a no-hassle setup and a clear fee structure. At Four, customers will make four payments over six weeks. Platform charges and late fees may apply. The Four team can walk merchants through fees and setup for their store. With Four, approval is decided per order, and not all applicants are approved. Results may vary.